 Chat on WhatsApp
ATX-UK exam format (June 2026 to June 2027 study guide)
| Part | What it contains | Marks |
|---|---|---|
| Section A | One compulsory case study covering more than one tax: 35 technical, 5 ethics and 10 professional skills marks | 50 |
| Section B | Two compulsory questions that together cover business and personal tax. Each has 20 technical and 5 professional skills marks | 2 x 25 = 50 |
| Total | 100 | |
| Pass mark | 50 | |
| Time | 3 hours 15 minutes, computer-based, with word processor and spreadsheet response options | |
| Tax law | Finance Act 2025 for the March and June 2027 exams |
What the ATX-UK syllabus covers
- A. UK taxes at an advanced level: income tax (including overseas aspects and trusts), capital gains tax, inheritance tax, corporation tax (including overseas, group and special company issues), stamp taxes, VAT and tax administration.
- B. Applying the taxes: how the taxes work in different situations and how they interact with each other.
- C. Tax planning: standard measures to reduce or defer tax, and the ethical issues in giving tax planning advice.
- D. Professional skills: communication, analysis and evaluation, scepticism and commercial acumen.
- E. Employability and technology skills: opening exhibits and using the word processor and spreadsheet to present your answer.
Two points to note. Stamp taxes (stamp duty, SDRT and SDLT) are new at ATX and are not in TX-UK. From June 2026, domicile, deemed domicile and the remittance basis are no longer examined. The foreign income and gains (FIG) regime and long-term UK residence for inheritance tax replace them.
Where marks are lost in ATX-UK
- Treating "state your assumptions" as optional. In the Sylvie question, many candidates skipped the assumptions they were asked for. Missing the business property relief condition, that the recipient still holds the shares (or has replaced them with other business property) at the donor's death, cost technical marks and a scepticism mark. When the task asks for assumptions, write them. (examiner's report, March/June 2026)
- Mixing up reliefs. Some candidates made gift holdover relief stricter than it is. They imposed a minimum 5% shareholding, which is not required for unquoted shares, or a two-year ownership rule borrowed from BADR or BPR. In the Kubba Ltd question, many discussed BADR, which does not apply to companies. Know which reliefs apply to companies, to individuals or to both, and keep CGT and IHT reliefs apart. (examiner's report, March/June 2026)
- Weak TX-UK basics. In Kubba Ltd, some candidates applied 26.5% to all profits between the limits instead of using marginal relief. Most missed that the former owner was an associated company. Very few explained the associated companies, and that cost about half the marks. The examiners say TX-UK knowledge must not be underestimated. (examiner's report, March/June 2026)
- Slow methods and answers outside the requirement. In the Esla question, most candidates prepared two full income tax computations. Full credit was available, but a marginal approach got there much faster, and only a minority used it. Write explanations where the task says explain or advise. Keep calculate tasks to the numbers. Material outside the requirement earns nothing. The same question showed that most candidates were not prepared for share incentive plans, so revise the less familiar topics too. (examiner's report, March/June 2026)
How our ATX-UK mocks work
- Pick your plan: Every Chapter Test Series (a test for every chapter and 2 full mock exams), Part-wise Test Series (5 part tests and 2 full tests), Full Syllabus Mock Tests (2 full tests) or Every Chapter Series + Mentor. All questions are original, written by our faculty in the current exam pattern, not ACCA past papers.
- The questions are original. They are not ACCA past papers.
- You attempt each mock under timed conditions and upload your answers.
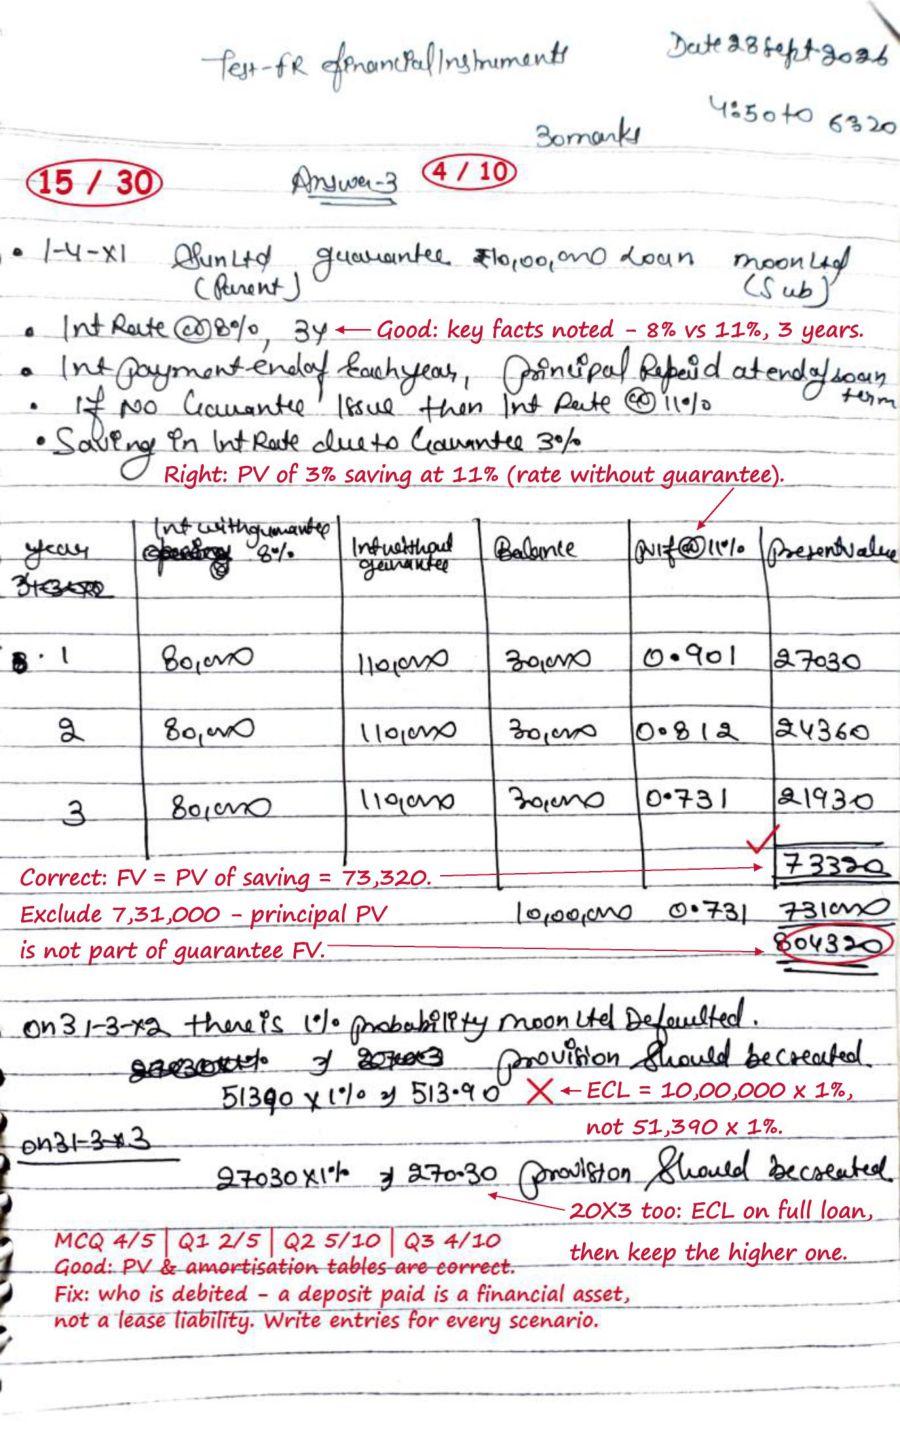
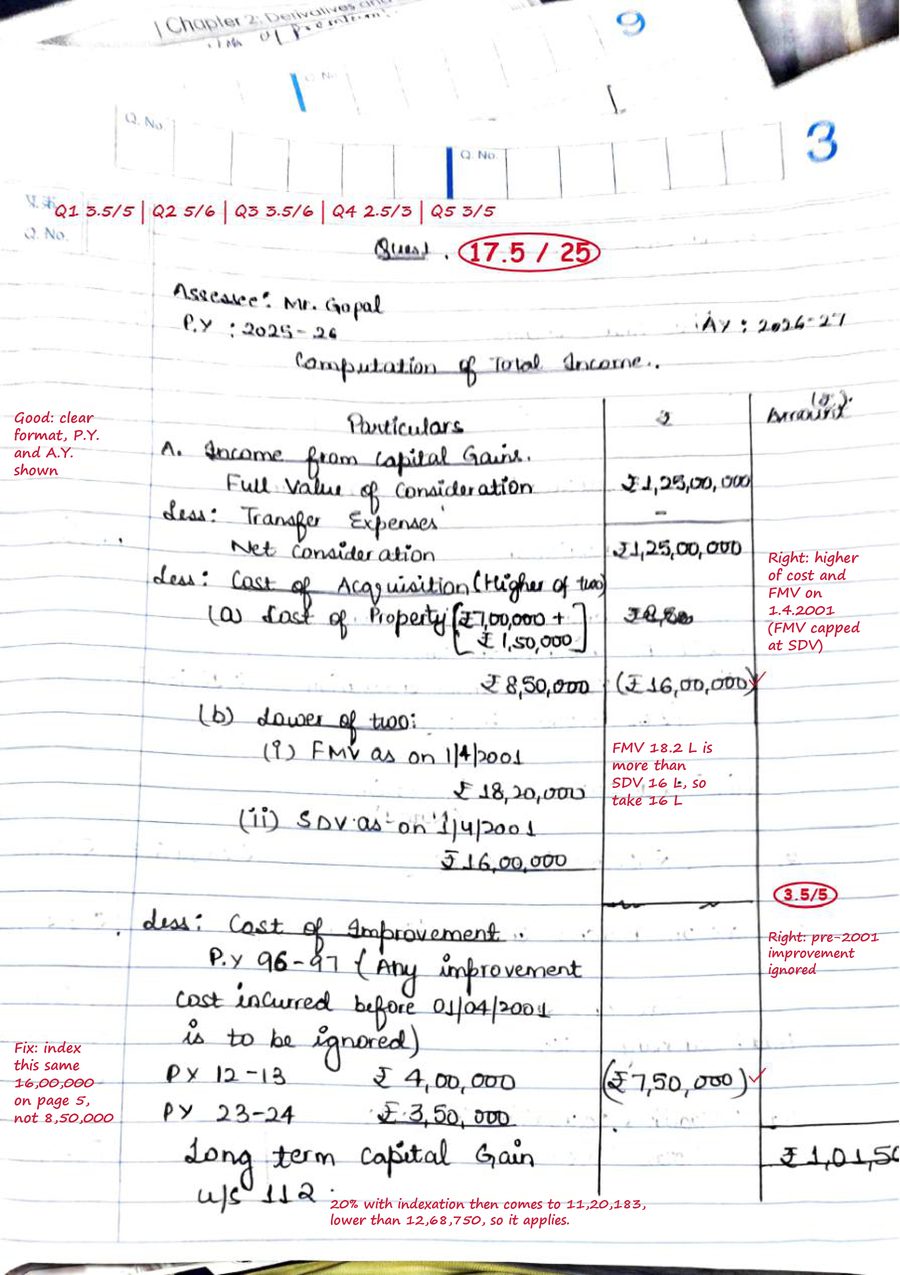
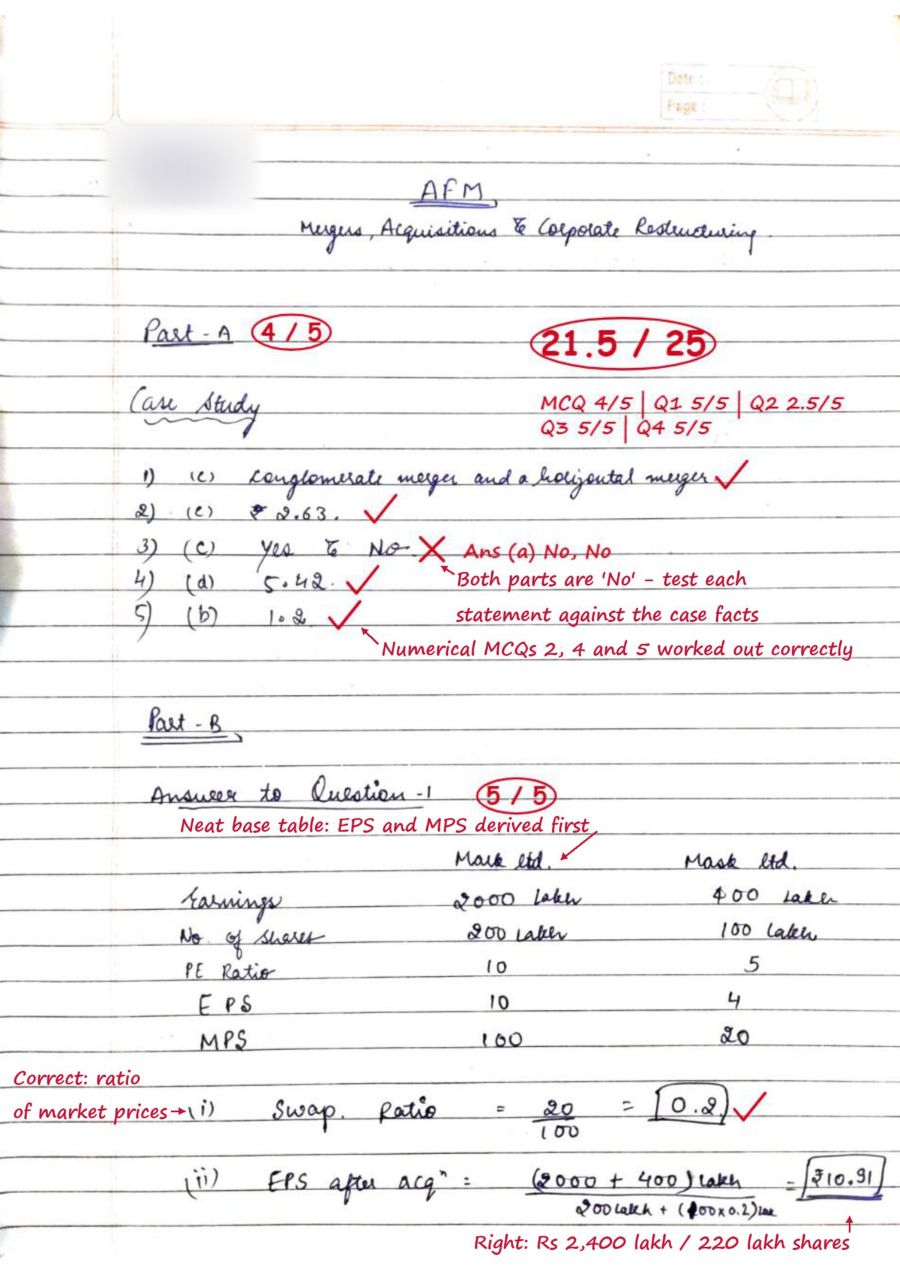
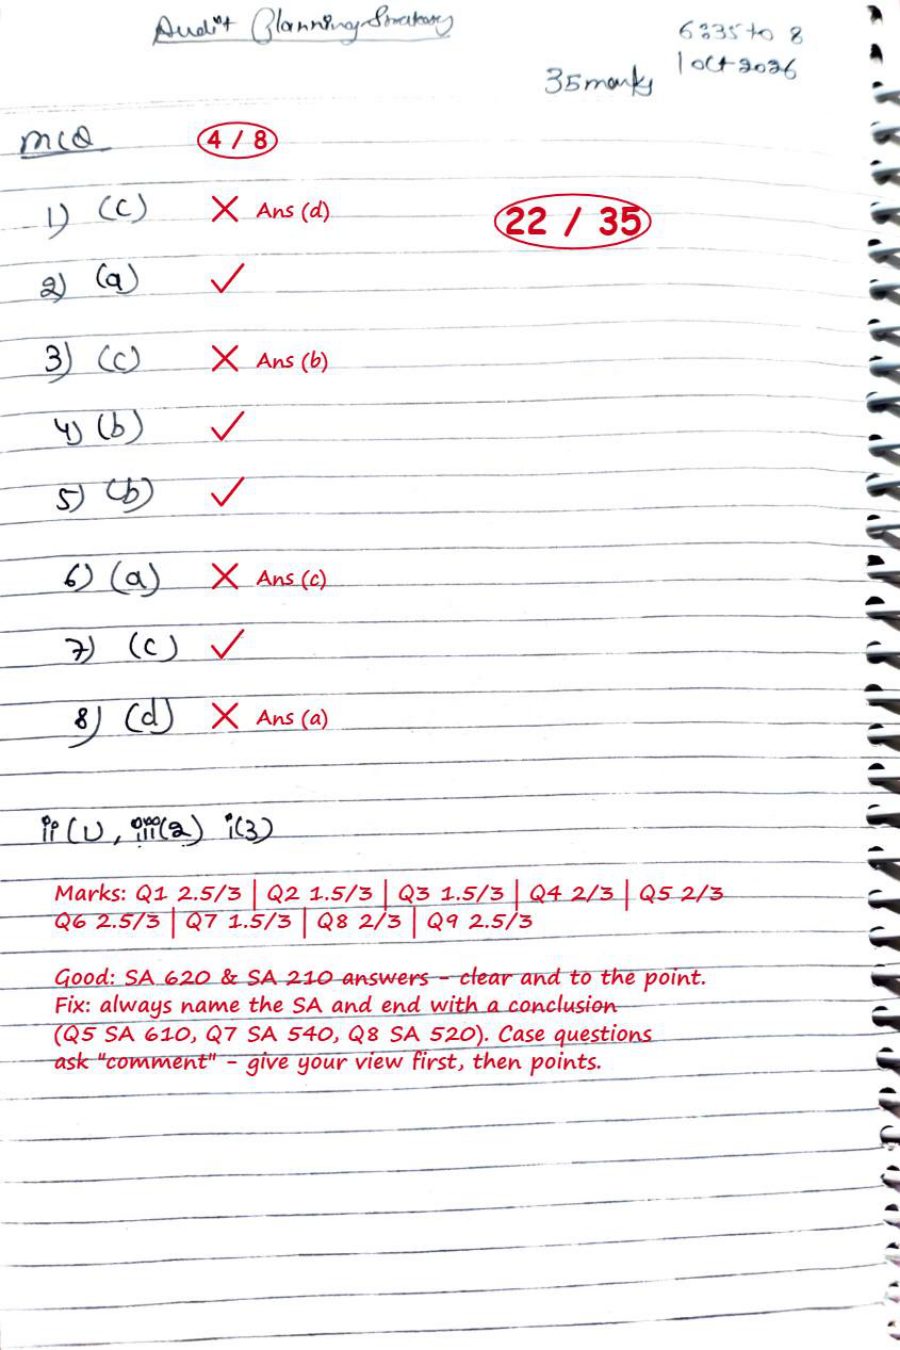
- Our faculty check your mock within 48 hours of upload. You get marks for each question and comments on what cost you marks.
- Our faculty answer your doubts on the checked mock.
- On the Every Chapter Series + Mentor plan, a mentor builds a week-by-week plan to your sitting and reviews your mock results with you.
What happens to ATX-UK in September 2027?
June 2027 is the last sitting of the current ATX-UK exam. From September 2027, ATX maps to STA Taxation Advisory Professional in ACCA's new structure, and passes you already hold carry across as credit. From then, only 1 option is needed at Strategic Professional.